Oak and Sunbed Hub

Tanning Salon Insurance

Oak helps UK sunbed and tanning salons consider suitable business insurance for their premises, equipment, liability, products, employees and business interruption. Cover is subject to insurer acceptance and policy terms.

For UK tanning salons

Built around the detail of running a salon.

Your premises, tanning equipment, products, treatments and staff all help shape your insurance needs. Oak can discuss these details with you and help present the business clearly to insurers.

Cover, limits and exclusions depend on the insurer, your salon's activities and the policy terms.

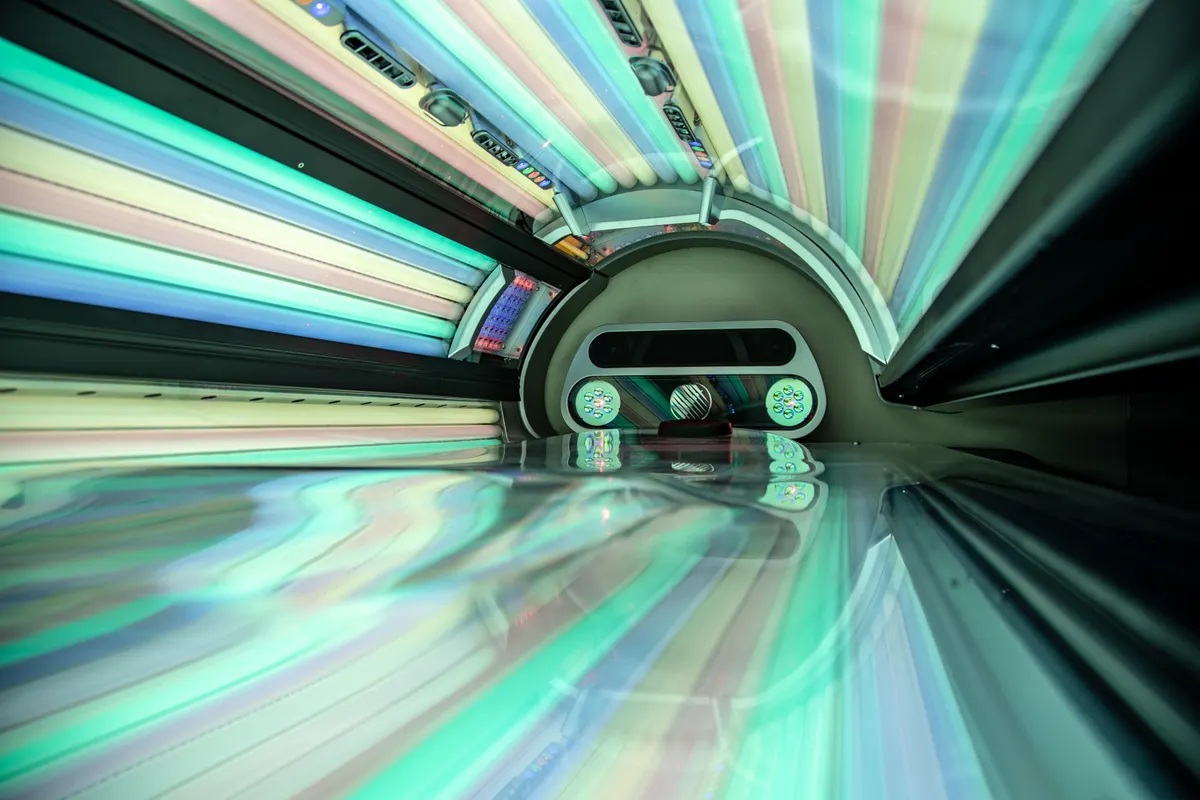
Interior of a commercial tanning sunbed with illuminated UV lamps
01Salon-specific information

Activities, equipment and operating controls.

02Insurance review

Suitable cover is subject to insurer acceptance and policy terms.

Cover to consider

Insurance shaped around your salon.

Discuss the cover your business needs. Suitable insurance is subject to insurer acceptance and policy terms.

01

Premises and equipment

Discuss buildings, fit-out, contents, tanning equipment and stock, including leased or financed units.

02

Liability, products and employees

Consider public and products liability alongside your workforce and employers' liability requirements.

03

Business interruption

Review income, ongoing costs and realistic recovery periods following insured damage, subject to policy terms.

Tanning Salon Insurance

Discuss your salon.

Leave your name, salon, email and phone number. Oak can contact you to discuss your business and insurance needs.

Submitting an enquiry does not put cover in place. Insurance is subject to insurer acceptance and policy terms.

A short, straightforward enquiry

Request a quote

Four short details are all we need to start the conversation.

Or email info@oak-insurancebrokers.co.uk or call 0330 133 4386.

Practical buying guidance

Describe every salon activity and the equipment used

A tanning salon may offer sunbed sessions, sell products and provide other beauty services. Tell Oak about all activities, whether sunbeds are staffed or otherwise operated, the number and type of units, and the premises arrangements. A generic retail description may not adequately explain the business.

Equipment can be expensive to replace and essential to revenue. Discuss ownership or leasing, replacement values, servicing and electrical inspection records. Property damage, equipment breakdown and interruption may have different triggers; none should be assumed to cover every equipment failure.

Customer liability, products liability and employers' liability need to be considered alongside the salon's operating controls. Insurance does not replace age restrictions, safety obligations or manufacturer instructions. Applicable rules differ across the UK and should be checked for the salon's location.

Compare the wording, not just the premium

Check the accepted salon activities, liability exclusions, leased equipment interests, breakdown wording and interruption basis. Suitable insurance remains subject to insurer acceptance and policy terms.